Managing money is one of the biggest sources of stress for young people — yet financial education rarely reaches them in a way they can use. The challenge, proposed in partnership with ING Bank, started from a real tension: a huge share of the Spanish population uses banks daily, but that doesn't mean they have financial literacy. Banking is full of complex terminology and products people don't understand, and young adults in particular feel overwhelmed by the sheer volume of financial content available while still lacking the practical, contextualized guidance to actually build healthy money habits.
The solution
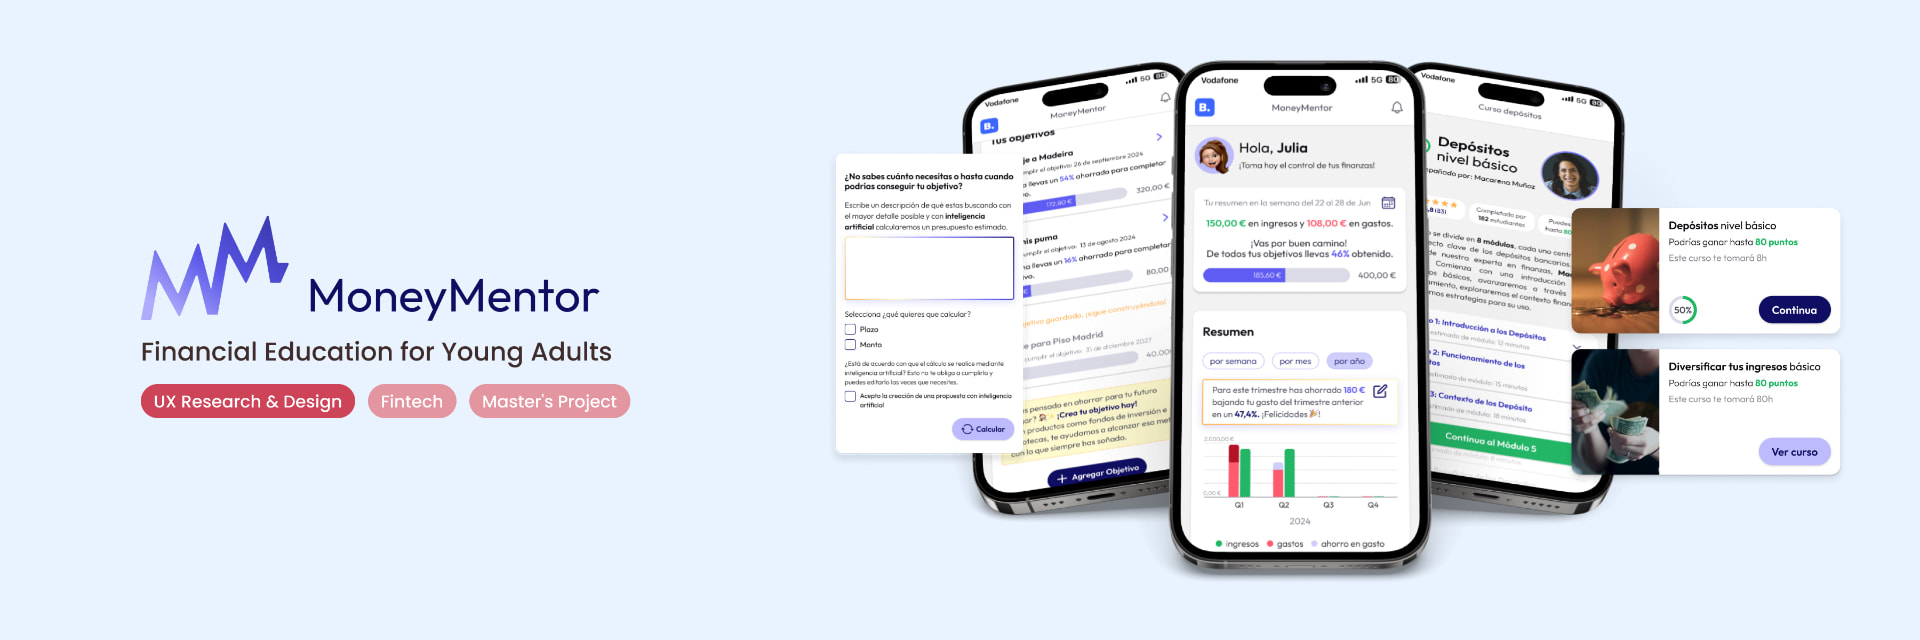
MoneyMentor — a bank-provided service that helps young people take control of their finances and build a healthy relationship with money. It's built around three pillars: a clear financial summary of income and spending, personalized goal-setting with AI-assisted budgeting, and gamified financial education. Instead of adding to the noise, it turns money management into something practical, motivating, and emotionally supportive — designed to reduce the guilt and anxiety young people so often attach to their finances.
Jhendí Pineda – Design partner, research & problem definition
Project timeline
May 2024
Secondary and primary research: financial-education landscape in Spain, gamification case studies, and in-depth interviews with students, teachers, parents, and finance experts.
May–Jun 2024
Insights, personas, and problem reframing through How Might We's.
Jun–Jul 2024
Co-creation facilitation session with real users, followed by service mapping: Journey (AS IS), Service Blueprint (TO BE), and Concept Map.
Jul 2024
Service architecture, benchmark of Spanish fintech platforms, and full Figma prototype.
MoneyMentor — key screens.
How might we help people internalize methods that let them resolve and take control of their financial decisions?
MoneyMentor reframed financial education around what young people actually need: practical, contextualized support that helps them act without adding more guilt or anxiety.
🏢 Business problem
Banks are part of young people's daily lives, but their terminology, products, and disconnected financial-education content rarely help customers build practical financial confidence.
👤 User problem
Young people feel insecure and overwhelmed by the volume of financial content around them. They need relevant, practical guidance and a coherent message from the people and institutions that influence their relationship with money.
Financial information overwhelms young peoplePractical, personalized and supportive guidance
🎯 My role
I led this project end to end as my master's thesis, applying the full user-centered design process from research to high-fidelity prototype. I ran the secondary and primary research, facilitated a co-creation workshop with real users, and translated everything into personas, journey maps, a service blueprint, and a working Figma prototype with its own design system. In the first diamond I worked alongside designer Jhendí Pineda on research and problem definition; from concept through delivery, the design and prototyping were my own.
•Led secondary and primary research
•Facilitated a co-creation workshop with real users
•Created personas, journey maps, and the service blueprint
•Designed the service architecture and product experience
•Built the high-fidelity prototype and its design system
User research
Information was everywhere. Practical guidance was not.
I combined two fronts. On the secondary side, I studied the state of financial education in Spain and the role of digital design and gamification, drawing on Nielsen's heuristics and cases like Duolingo, Khan Academy, and Zogo. On the primary side, I ran semi-structured in-depth interviews across four groups: students, teachers, parents, and finance experts — a sociologist-economist and a market-research consultant. A consistent picture emerged: young people feel insecure and overwhelmed, want practical and relevant learning, and carry a quiet sense of guilt around money, while their environment — family, teachers, banks, and social media — sends them no shared, coherent message.
MoneyMentor research and workshop boardDrop image here
Journey map
From reactive money management to proactive decisions
I clustered the raw findings into key themes — perception of need, curriculum, new technologies, influence, risk, motivation, and learning methods — and distilled them into insights. From four of those — short-term thinking, interest and motivation, practical learning, and guilt — I reframed the problem: how might we help people internalize methods that let them resolve and take control of their financial decisions? I then built a persona, Julia, a 19-year-old design student, and mapped her Customer Journey AS IS across a full week, surfacing how reactively she manages money and how her emotions swing between worry and guilt. A Service Blueprint TO BE then showed how the right tools, notifications, and bank-system logic could move her from reactive to proactive.
MoneyMentor habit journey mapDrop image here
Design + iterations
Communicate to solve, never to blame
To generate solutions I facilitated a structured co-creation session with real users, using empathy mapping, nominal brainstorming, NUF prioritization, and 5Ws to pressure-test ideas. The strongest concepts converged into MoneyMentor. I benchmarked leading Spanish fintech apps — Revolut, Fintonic, and Banktrack — against Nielsen's heuristics to learn what already worked in visualizing finances and gamifying learning, then designed the full prototype in Figma with its own design system: a financial summary with editable spending goals and clear income and expense graphs, an AI-assisted goal-creation flow with product recommendations, and a gamified education area with courses, tests, points, and badges. Throughout, one principle guided the tone: communicate to solve, never to blame.
MoneyMentor design system and final prototypeDrop image here
Outcomes and impact
MoneyMentor delivered a complete, research-backed service concept and high-fidelity prototype that reimagines how a bank could support young people's financial independence, bringing a clear money summary, practical goal-setting, and gamified learning into one experience designed around a healthier, less anxious relationship with money. As my thesis project, it became the foundation of the work I went on to do in fintech and connected directly to the ING investment-area project I joined shortly after.
What I learned
I learned how much a rigorous, user-centered process can reveal that assumptions can't. The interviews reframed the whole problem from "young people lack information" to "young people are overwhelmed by it and carry guilt around it." I saw the value of flexibility: when recruiting the exact target persona for the workshop proved impossible, widening the participant profile actually enriched the results. And I came away convinced that in finance, empathetic, non-judgmental communication matters as much as the features themselves — designing for someone's emotional relationship with money, not just their tasks. I also learned to hold a rigorous process together under real time pressure — delivering the full Double Diamond, from primary research to prototype, in an intense three-month stretch without letting the depth of the work slip.
Want the full walkthrough?
Happy to walk you through the research, the iterations and the final screens in detail.